A good share of the calls that reach our office begin with an adult child rather than the person who will be wearing the pendant. The safety conversation has usually already happened. The money conversation has not, and it tends to surface about ninety seconds in, disguised as a billing question: can this go on my card instead of my mother’s?
It is a small question carrying a large one.
Behind it sits a family quietly reorganising its finances around a parent’s care, often without anyone saying so out loud. The scale of that reorganising is documented now. The National Seniors Council’s 2025 brief on caregivers of older adults, drawing on the Canadian Centre for Caregiving Excellence’s national caregiving survey, reports that almost one in four caregivers spend more than $1,000 a month out of pocket on care. The same brief cites Statistics Canada’s 2024 finding that 13.4 million Canadians, roughly 42 percent, provide unpaid care to a child or to an adult who needs it.
Inheritances are shrinking against that. Families who assumed they were managing an estate find they are financing a care plan instead.
What the money is actually buying
Families rarely budget for “care.” They budget for a list of separate things that happen to land in the same month: a few hours of help with bathing, a drive to a clinic, a grab bar for the tub, a phone line that gets answered at three in the morning.
Assembled, those line items purchase one thing. Time at home.
The preference driving that spend is well measured. The National Institute on Ageing’s 2024 survey found 80 percent of Canadians aged 50 and older plan to support themselves to live safely and independently in their own home for as long as they can, rising to 86 percent among those aged 80 and over. So a family working through these numbers is choosing which version of the next five years it is paying for, and the spending follows from that choice rather than the other way round.
Who pays, and in what order
There is a rough order of operations that Canadian families tend to land on, usually after a few months of improvising.
First, the parent’s own income and savings. Adult children often try to skip this step out of kindness, and skipping it backfires twice over. Money spent on staying independent is money doing precisely the job it was saved for. Treating the parent as the payer also keeps them inside the decision, which turns out to matter enormously for whether the plan survives contact with reality.
Second, the public and community programs. Provincial home-care programs, community support services, and municipal transportation and meal services carry a real share of the load. Eligibility varies by province and often by region within a province, and intake generally runs through a case worker or a hospital discharge team rather than a form you can fill in yourself. Bedford Medical Alert® is a member of the Ontario Community Support Association, the body representing the home and community care agencies that deliver much of this work in Ontario, and the standing advice from that sector is the same every time: begin the intake conversation before you need it, because assessments and waitlists do not compress in an emergency.
Third, the family. This is where the arithmetic stops being abstract, and where most of the friction lives.
None of the above is financial or legal advice. The tax and estate side in particular deserves a professional, and an accountant or an elder-law lawyer generally costs less than the mistake they prevent.
The line items families forget
- Recurring service subscriptions, and whether equipment is included in them or billed separately on top.
- Home modifications. Grab bars, a second stair rail, better lighting at the top of the stairs.
- Transportation to appointments once driving stops. This one grows quietly.
- The caregiver’s own lost income, reduced hours and missed pension contributions.
- Tax credits. The Canada caregiver credit is a non-refundable federal credit, and several provinces run their own programs alongside it. We have covered that ground already in Canada’s caregiver tax credit, so the only thing to add here is timing: check before you file, not after.
The Canadian Centre for Caregiving Excellence’s 2024 findings, cited in the same federal brief, are worth sitting with on this point. One in ten caregivers report leaving bills unpaid or paying them late, and drawing down long-term savings, in order to keep care going. The out-of-pocket layer is not incidental.
Working out what a safety plan would actually cost your family? Call us at 1-888-755-3055 and ask. We will walk you through what is included, what it runs monthly, and what the options are, with no obligation to buy anything at the end of it. If a different arrangement suits your parent better, we will say so.
Sharing the cost between siblings without a standing argument
Four ground rules keep cost-sharing from curdling. They are unglamorous, and they work.
One payer of record. One person’s card, one account, one statement, with everyone else settling up to that person. Splitting a single service across three siblings creates three separate chances for it to lapse at the worst possible moment.
Write it down. A shared document listing who pays what, updated whenever it changes. Memory is a poor accountant, and stress makes it considerably worse.
Count the contributions that never appear on a statement. The sibling who lives twenty minutes away and handles every appointment, every prescription pickup and every 6 a.m. phone call is contributing a great deal. Say so explicitly and early, because the alternative is that it gets said late and badly.
Set a revisit date. Care needs change. A split agreed in March should be looked at again in September rather than quietly resented until Christmas.
One more thing, and it is the one we would argue hardest for: keep the parent in the room for these conversations as long as they are able to be. Decisions made with someone hold up better than decisions made about them. In our experience the difference eventually shows up in something very concrete, which is whether the equipment actually gets worn once it arrives.
Where a monitoring subscription sits in the budget
Set against a retirement residence, or several hours a week of paid personal support, monitoring is one of the smaller lines on the page. Its job is narrow and specific: shorten the gap between something going wrong and somebody knowing about it.
How ours is structured, since structure is what decides whether a subscription becomes a budgeting problem:
- Equipment is included with the subscription. There is no separate device purchase to find room for.
- No long-term contracts. Plans run month to month or annually at the customer’s choice, with a three-month minimum at the start and optional six or twelve month initial terms if the savings suit you. Service always reverts to month to month, and there are no cancellation fees. The reasoning behind that is in medical alert systems in Canada with no contract.
- Monitoring is 24/7 and based in Canada. Our operators work from a personalized response plan written for each subscriber rather than a generic script: who gets called, in what order, who holds a key, what the person’s circumstances are.
- For a straight cost breakdown rather than a family-finances one, see medical alert costs and coverage in Canada.
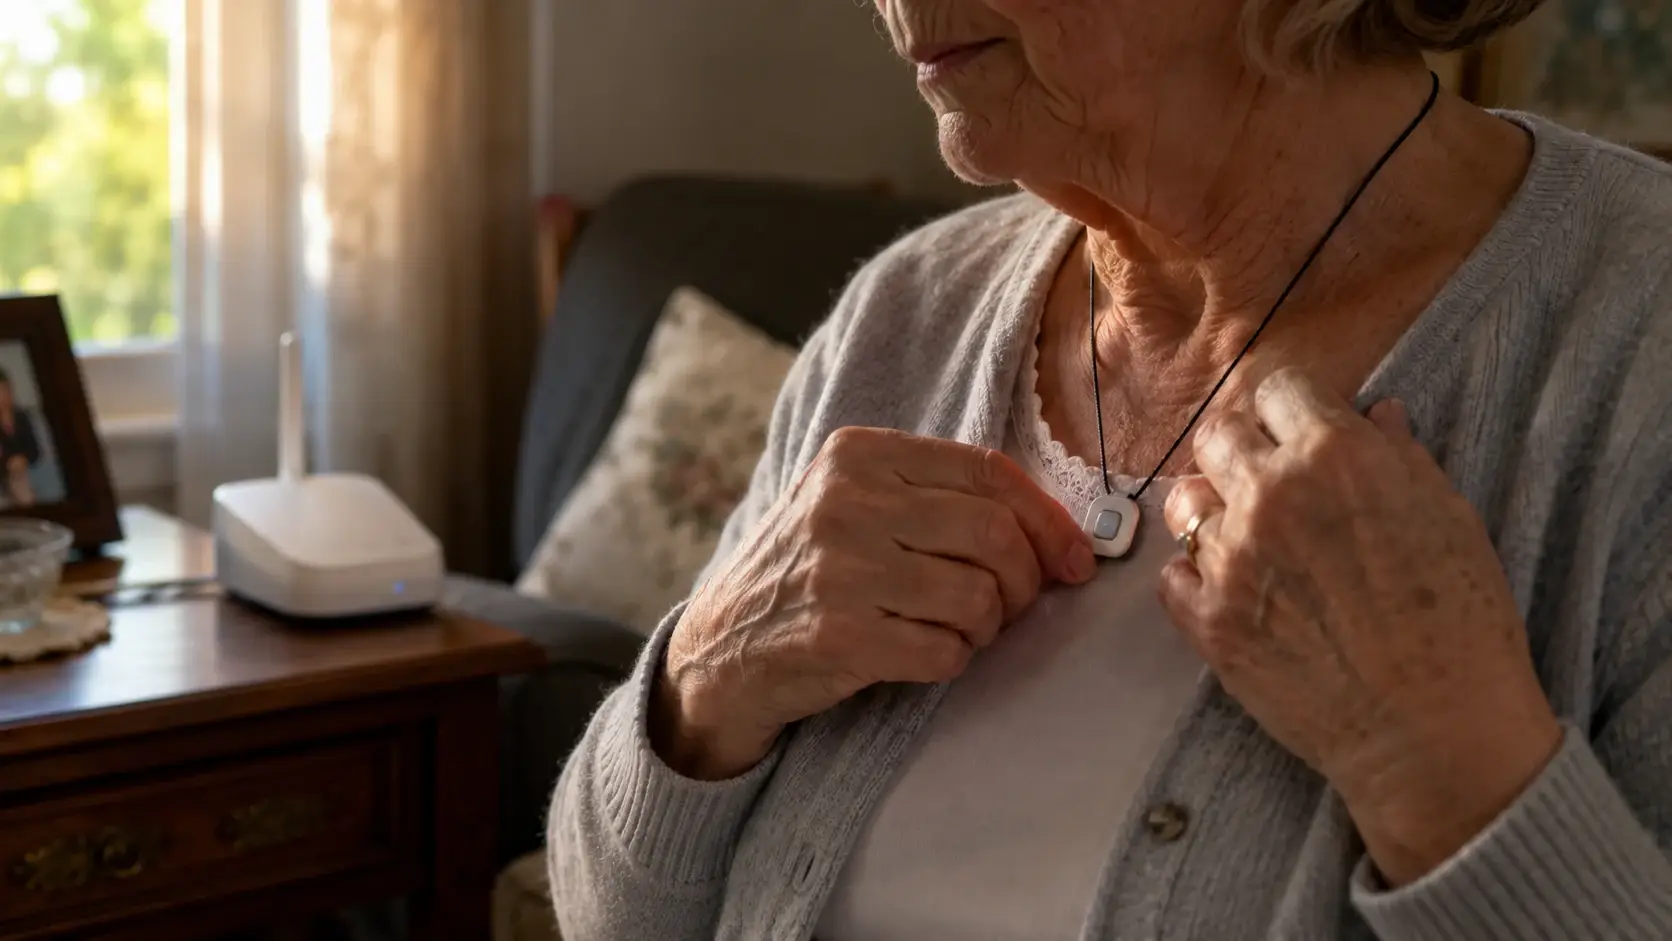
For a parent staying in their own home, Home Freedom is the usual starting point: an in-home base unit paired with a pendant, covering the rooms where people actually spend their days. Bedford has supported hospital education programs and research initiatives from UHN Toronto Rehab to Trillium Health, and brings three generations of experience to this work, which is a roundabout way of saying we have watched a great many families do this arithmetic.
Three things to have ready before the next family call
A real number for your parent’s monthly income and fixed costs. Not an estimate, and not a number from four years ago.
A written list of what care is genuinely needed this year, kept separate from what might be needed in three. Families routinely price the second list, look at the total, and panic about a situation that has not arrived.
One question answered out loud. If staying at home costs more than the alternative for a stretch, is the family prepared to pay for that? Sometimes the answer is no. That is a legitimate answer, and knowing it in a calm month beats discovering it in a bad week.
If aging in place is the direction you are heading, our guide to aging in place in Canada covers the parts of that decision that are not about money.
And if the money conversation is happening early, while your parent is still well, our page on planning ahead for aging parents covers the decisions that age best when made in an unhurried season.
If you are caring for a parent and for children at the same time, the national figures on how many Canadians share that position, and how many hours a week it takes, are on the sandwich generation in Canada.
If your parent is staying in their own home, our Home Freedom system is the place most Canadian families begin: an in-home base unit and a pendant, 24/7 monitoring from right here in Canada, equipment included, and no long-term contract. Call 1-888-755-3055 to talk it through with someone who will give you a straight answer about cost, or to arrange a complimentary consultation by phone.